
Practical Aspects of UAE Corporate Income Tax
A conference presentation on the practical operation of the UAE Corporate Tax regime, from taxable persons and free-zone treatment to transfer pricing and anti-abuse rules.
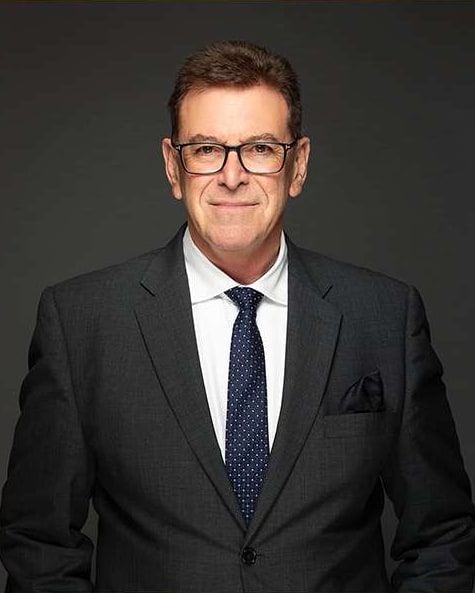
Dr Peter Wilson
Founder
· 11 min read
Presentation for the ACCA SMP Conference, 9 March 2023
Dr Peter Wilson, PB First Global Tax
Dr. Peter Wilson is Australian by birth, and has lived in Sydney, London, New York and in Dubai since 2016. For more than 40 years, he has advised a wide range of MNEs, Governments, UHNWIs and Financial Institutions on the international tax law applicable to trading and investment activities as well as to ownership.
He has formal qualifications in taxation, chartered accounting and law and a PhD in ‘BRICS and International Tax Law’ from Queen Mary, University of London, 2017. For many years, Peter was an EY International Tax Partner (Sydney, London and New York) and later PwC (London) and an Investment Banker at a major Japanese Financial Institution. Since 2016 Peter has run PB First Global Tax in Dubai.
Presentation agenda
- Transitional arrangements
- Record keeping
- Language
- Payment of taxes
- Clarifications
- Taxable persons
- Qualifying Free Zone income
- Carry-forward losses
- Anti-avoidance
Quiz time
Transitional Arrangements
Background: The First Tax Period opening Balances are the previous year closing balances. The Tax Calculation of the First Tax Period assumes that related party transactions entered into in the previous year were conducted on an arm’s length basis.
Question: Y Company LLC’s financial statements for the Year Ending 31 December 2023 contain service fee income derived from a Qatar based related company.
The fees for the services were charged under a 5-year services agreement entered into on 1 January 2022.
When Y Company LLC’s auditors reviewed the company’s financial statements for the 2022 statements they detected the service fee was calculated at cost without a profit margin.
If the service fee basis is not adjusted for the 2023 Accounting Period the opening balance in the 2024 Accounting Period will not be impacted for an accrual taxpayer?
True or False?
Background: The First Tax Period opening Balances are the closing balances of the previous Year.
The Tax Calculation of the First Tax Period assumes that related party transactions entered into in the previous year were conducted on an arm’s length basis.
Question: Y Company LLC purchased a ceramic tile cutting machine from its Qatar related company on 30 June 2022 for AED10,000,000 when the fair market value of that machine was AED7,500,000.
Y Company LLC does not impair the cost in its books as at 31 December 2023.
Will Y Company LLC’s 1 January 2024 opening written down balance on that machine need to be adjusted before calculating the book charge?
Yes or No?
Record Keeping
Background: Decree-Law 47 of 2022 requires books and records to be kept for 7 years following the year in which the transactions occurred Tax Procedures Executive Regulations No 7 of 2017 requires books and records to be kept for 5 years following the year in which the transactions occurred.
Question: X Legal Consultant LLC’s books and records for Tax Period 2023 were thrown away in the 2029 Tax Period.
Is X legal Consultant in breech?
Decree-Law 47 of 2022 requires books and records to be kept for 7 years following the year in which the transactions occurred
Question: In 2018 Y Clothes Manufacturer LLC built a fashion factory in Deira for which it paid AED2,000,000 for dress cutting machine and was given a 24 months warranty by the manufacturer of that machine.
In 2022 the LLC disposed of the invoices and manuals received from the manufacturer of the machine. Y Clothes Manufacturer LLC depreciates the machine in its books at 15% each year straight line.
In 2024 the FTA questioned the cost price and requested Y Clothes Manufacturer LLC supply invoices and other paperwork to justify the cost. Having disposed of the materials after the 5 years is Y Clothes Manufacturer LLC in breech?
Language
Background: Under the Tax Procedures Decree Law 2022 every Person submitting a Tax Return and any data, information, records and documents related to Tax that he is required to submit or otherwise requested to submit to the FTA must be in Arabic. The FTA may accept the materials and return in any other language, provided the Person provides the FTA with an Arabic translated copy if requested by the FTA.
Under the Tax Procedures Executive Regulations 2017 the materials relating to any Tax are submitted to the FTA in Arabic and maybe submitted in English. In that instance an Arabic translation is required if the FTA requests. If the materials relating to any Tax are issued in any foreign language other than English, the Person is required to translate into Arabic and then submit them to the FTA
Question: P Pantry DMCC’s employees speak Russian only and all their suppliers only speak Russian and they work with a Russian speaking Sharjah accounting Firm. Will supplying the materials to the FTA only in Russian without preparing an Arabic version be acceptable?
Payment of Taxes
Background: Under the Decree-Law 47 of 2022, the tax due is paid no later than 9 months after the end of the Tax Period and the amount payable is the total of the corporate tax already deducted plus the withholding tax plus the foreign tax credit.
Under Tax Procedures Decree-Law 28 of 2022, when a Taxable Person makes any payment without specifying the type of Tax or the Tax Period, the FTA has the right to allocate the full amount or part thereof for settlement of Tax or amounts due, as specified in the Executive Regulations.
Question: X Legal Consultants prime tax liability for the Tax Period 31 December 2025 India on which that tax had been deducted.
Is this amount to be paid to the FTA by 30 September 2026?
Background: Under the Decree-Law 47 of 2022, the tax due is payable no later than 9 months after the end of the Tax Period. The amount to be paid is the total of the corporate tax already deducted plus the withholding tax plus the foreign tax credit.
Under the Tax Procedures Decree-Law 28 of 2022, if a Taxable Person makes any payment without specifying the type of Tax/Tax Period, the FTA has the right to allocate the full/part amount for settlement of Tax or amounts due, as specified in the Executive Regulations.
Question: X Legal Consultants prime tax liability for the Tax Period 31 December 2025 amounts to AED5,000,000 and assume it owes the FTA AED1,000,000 for the Accounting Period ended 31 December 2024.
If X Legal Consultants does not nominate the AED5,000,000 as being the 2025 tax liability does the FTA have the right to apply AED1,000,000 to firstly pay the 2024 debt leaving the company short paying the 2025 tax by AED1,000,000?
Clarifications
Background: Under Article 59 Decree Law 47 of 2022 a Person may make an application to the FTA for a clarification regarding the application of the Decree- Law 47 of 2022 or the conclusion of an advance pricing agreement with respect to a transaction or an arrangement proposed or entered into by the Person.
Question: X Legal Consultants requests the FTA to clarify whether two persons relationship is such that they are related and therefore require arm’s length pricing and an advanced pricing agreement covering fees charged by X Legal Consultants to the DIFC branch of a Sharjah company.
Should the parties expect this clarification to be of a kind to which Article 59 is directed?
to an Indian company.
Question: P Pantry Pies DMCC sells scones and jam to a 5-star hotel on Palm Jumeriah. The Hotel business is run by a company based in DMCC.
P Pantry DMCC is unsure whether the revenue from the sale of scones is DMCC income or mainland income.
Should the parties expect this clarification to be of a kind to which Article 59 is directed?
Taxable Persons
Background: A Taxable Person is subject to Corporate Tax under Decree-Law 47 of 2022 Under Article 16(1) of the Decree Law, an Unincorporated Partnership shall not be a Taxable Person in its own right, and Persons conducting a Business as an Unincorporated Partnership are treated as individual Taxable Persons under the Decree-Law.
Under Article 4 of the Decree Law, a range of Government and specified persons are exempt from being Taxable Persons including a Qualifying Public Benefit Entity, Qualifying Investment Fund, a pension or social security fund, or a juridical person incorporated in the State that is wholly owned and controlled by an Exempt Person.
Question: A natural person earning salary as an employee is a taxable Person?
Question: A DIFC Investment Fund managed by a UK regulated Manager is a Taxable Person?
Question: A French incorporated company which is a partner in a UAE Unincorporated Partnership which derives license fees from a RAK Free Zone IP company is a Taxable
Question: A UAE Mainland LLC with a branch in Malta on which Malta corporation tax is paid is not a Taxable Person?
Qualifying Free Zone Person
Background: A Free Zone Person that meets the conditions of Article 18 of Decree-Law 47 of 2022 and is subject to Corporate Tax under Article 3(2) of the Decree-Law A Qualifying Free Zone Person is a Free Zone Person which under 18(1) of the Decree Law (a) maintains adequate substance in the UAE, (b) derives Qualifying Income as specified in a decision issued by the Cabinet at the suggestion of the Minister, (c) has not elected to be subject to Corporate Tax under Article 19 of the Decree-Law, (d) complies with arm’s length pricing and transfer pricing documentation and (e) meets any other conditions as may be prescribed by the Minister.
Question: A Ras Al Khaimah Free Zone company deriving dividends from stock owned in a German company has a flexi desk and has not elected Article 19 status.
Is the company a qualifying free zone person?
Question: A Fujairah Fee Zone company, wholly owned by two natural persons living in Arabian Ranches, provides architectural services to client companies on the UAE Mainland, Sharjah, Qatar and Morocco.
The company’s architects are all based in downtown Dubai. Is the company a qualifying free zone person?
Question: The same Fujairah Fee Zone company, provides architectural services to related companies on the UAE Mainland, Sharjah and Morocco.
The fees charged by the Fujairah Free Zone Company are calculated exclusive of profit margin and confirmed by a two line Board resolution. Is the company a qualifying free zone person?
Carry Forward Losses
Background: Under Article 39 Decree Law 47 of 2022 tax Losses can only be carried forward and utilised if (a) from the beginning of the Tax Loss year to the end of the Tax Period of the Tax claim year the same Person or Persons continuously owned at least a 50% ownership interest in the Taxable Person or (b) the Taxable Person continued to conduct the same or a similar Business or Business Activity following a change in ownership of more than 50%.
Relevant factors determining whether a Taxable Person conducted the same or a similar Business or Business Activity following a change include (a) the Taxable Person uses some or all of the same assets as before the ownership change, (b) the Taxable Person has not made significant changes to the core identity or operations of its Business since the ownership change and (c) where there have been any changes, these result from the development or exploitation of assets, services, processes, products or methods that existed before the ownership change.
Question: A Mainland LLC was owned by Joe and his brother Fred 60% and 40% respectively from incorporation on 1 January 2021 to 31 January 2024 when Fred purchased Joe’s 60%.
Does A Mainland LLC satisfy the continuing ownership test?
Question: The owners of B Mainland LLC, are carrying on a retail shoe business in Business Bay, Deira and Abu Dhabi. They sell 100% of the stock in the company to Joe Banana.
Joe Banana closes the Deira branch and ceases selling shoes in Business Bay and Abu Dhabi and commences selling gym wear with 15% of the store footage retained for shoe sales.
B Maitland incurred AED1,000,000 losses. Does B Mainland LLC satisfy the same or similar business test?
Anti Avoidance
Background: Under Article 50 Decree Law 47 of 2022, a transaction or an arrangement is proscribed if, having regard to all relevant circumstances, it can be reasonably concluded that (a) the entering into or carrying out of the transaction or arrangement, or any part of it, is not for a valid commercial or other non-fiscal reason which reflects economic reality and (b) the main purpose or one of the main purposes of the transaction or arrangement, or any part of it, is to obtain a Corporate Tax advantage that is not consistent with the intention or purpose of this Decree-Law.
A Corporate Tax advantage includes, (a) a refund or an increased refund of Corporate Tax, (b) avoidance or reduction of Corporate Tax Payable, (c) deferral of a payment of Corporate Tax or advancement of a refund of Corporate Tax (d) avoidance of an obligation to deduct or account for Corporate Tax.
Question: A company restructured its business in order that its Free Zone or non UAE income was assigned to a newly formed Free Zone company in order to qualify for the 0% rate of tax.
The mainland income remained with the LLC. There was no other reason for the restructure. Did this restructure give rise to a Corporate Tax Advantage?
Question: Joe and Fred owned 5 companies together with each owning 40% stock ( i.e., 80% together) while Fred’s uncle Billy owned the remining 20%.
One of the companies had tax losses while 4 others had profits. Three of the companies disaggregated the building chain, the fourth employed the labours which was provided and charged to the other 3 and the 5th marketed the dwellings to retail customers. Joe, Fred and Billy formed a tax Group.
Did the group formation give rise to a Corporate Tax Advantage?
Thank you.